 International
 Kenya
 South Africa
 Australia
 New Zealand
 China
 Hong Kong
 Japan
 Macau
 Mongolia
 South Korea
 Taiwan
 Austria
 Belgium
 Czech Republic
 Denmark
 France
 Germany
 Ireland
 Italy
 Netherlands
 Norway
 Poland
 Spain
 Sweden
 Switzerland
 Turkey
 United Kingdom
 Saudi Arabia
 United Arab Emirates
 Canada
 Mexico
 United States
 Bangladesh
 India
 Sri Lanka
 Cambodia
 Indonesia
 Malaysia
 Philippines
 Singapore
 Thailand
 Vietnam
Whether you are considering a career opportunity, retirement or a change of surroundings, moving from the Netherlands to France offers plenty of possibilities. Your experience will depend on the location you choose your household’s needs and how well you prepare for the practical differences.
For Dutch citizens, EU free-movement rights simplify the immigration side of relocation. However, healthcare, housing, schooling and departure arrangements in the Netherlands still require attention.
This guide explains what to consider before moving and how to prepare for everyday life in France.
TL;DR: La vie en France
- Dutch citizens do not need a visa to move to France, but conditions apply when staying for more than three months.
- Non-EU nationals living in the Netherlands must check their own French immigration requirements.
- Compare housing and household expenses for your chosen location rather than assuming France will be cheaper.
- Arrange healthcare according to your employment, pension or residence situation.
- Research schools early and allow time to prepare documents and French-language support.
- Include Dutch departure administration and the transport of your belongings in your moving plan.
Before You Move: Residence Rights and Immigration
Dutch citizens can live and work in France without a visa or work permit. For stays beyond three months, your circumstances determine the conditions you must meet:
- Employees and self-employed people: You can establish residence through your professional activity.
- Students: You generally need enrolment at an eligible institution, health insurance and sufficient resources.
- Retired or economically inactive people: You generally need sufficient resources and comprehensive health cover.
A French residence card is optional for EU citizens. After five years of lawful, continuous residence, you can generally acquire permanent residence rights, subject to the applicable conditions. See the French government’s guidance for European residents.
What if you are not a Dutch or EU citizen?
A Dutch residence permit does not automatically authorise you to settle or work in France. Your route may depend on your nationality, family relationships and the type of residence status you hold.
Before booking your move, check whether you require French permission for employment, study, family reunification or another purpose. EU family-member and long-term-resident provisions can affect the process, so use the official France-Visas service to check your circumstances.
Prepare passports or identity cards, employment or study documents, accommodation evidence and relevant family records. Ask the receiving organisation whether translations are required.
Also check your departure obligations with your Dutch municipality, insurer and other service providers.
Cost of Living and Housing: How Much Does It Cost to Live in France?
Your French budget will depend on more than the country itself. Property size, location, commuting, childcare and heating can make a substantial difference to monthly spending.
Compare your current household budget in the Netherlands with realistic costs for the neighbourhoods you are considering. Include one-off expenses such as moving services, deposits, temporary accommodation and furnishing your new home.
Housing
Rent and housing costs depend on several factors, such as location and home type*:
| Paris | As the capital and largest city, rents are significantly higher; a one-bedroom apartment in the city-centre averages at €1,386pm, rising to €3,019pm for 3 bedrooms. Outside central Paris, the costs fall to €1,065-€1,985. |
|---|---|
| Lyon | Known for its cuisine and culture, Lyon offers that cosmopolitan lifestyle that Paris provides for a smaller price tag, with rents ranging from €600-€1,610pm. |
| Bordeaux | The “wine capital of the world” is a popular destination for expats drawn to its rich culture, beautiful scenery, and high quality of life. It’s also less expensive than other cities, with average rents ranging from €670-€1,555pm. |
| Marseille | Rental prices in this historic port city are significantly lower than in Paris (nearly 30%!). Average costs range from €570-€1,385pm. |
| Nice | A popular destination for retirees, Nice offers a picturesque coastal setting, mild weather, and a vibrant international community ranging anywhere from €850-€1,600pm. |
*Please note: prices are accurate as of October 2026 and are subject to change. Always be sure to check current listings for comparable properties rather than relying on a single citywide average. Ask whether the advertised rent includes building charges, water or heating.
For rental applications, prepare identification, employment details and evidence of income. Ask agents what documentation they accept from applicants arriving from the Netherlands.
If you are buying, obtain a complete estimate of acquisition costs and ongoing ownership expenses before committing.
Utilities
Build your household budget around the actual property. Ask for its energy-performance information, heating type and available evidence of previous consumption.
Your checklist should include:
- Electricity and gas, where applicable.
- Water and wastewater charges.
- Broadband and mobile services.
- Home insurance.
- Building or shared-service charges.
- Applicable local taxes and waste-collection charges.
Do not assume that “charges included” means every bill is covered. Ask which services are included and whether payments are fixed or later adjusted.
Taxe d’habitation has been abolished for main residences, although it can still apply to second homes. It should not be treated as a standard monthly waste-collection charge. See the official housing-tax guidance.
 Healthcare and Insurance
Arrange healthcare before leaving the Netherlands. The country responsible for your cover depends on factors such as where you work, where you live and whether you receive a pension.
Someone taking a French job may have different arrangements from a pensioner or an employee temporarily posted by a Dutch company. The EU’s health-insurance guidance for people living abroad explains these distinctions.
PUMa (Universal Health Protection)
Protection universelle maladie, usually called PUMa, provides access to French statutory healthcare through employment or qualifying stable and lawful residence.
People working in France can generally qualify through their work without waiting three months. For people applying through residence, a three-month residence period generally applies, with exceptions and additional conditions. Confirm your position with your local health insurance office, usually the Caisse primaire d’assurance maladie, or CPAM. See the official PUMa guidance.
Reimbursement varies by treatment, official tariff and individual circumstances. Avoid assuming that the system pays a fixed percentage of every medical bill.
If the Netherlands remains responsible for your healthcare, you may need an S1 form to register your entitlement in France. This can apply to eligible pensioners and certain posted workers. Check with the relevant Dutch institution before cancelling existing cover. EU guidance explains how S1 registration works.
Mutuelle
A mutuelle, or complementary health policy, can help cover eligible costs remaining after statutory reimbursement.
When comparing policies, ask about:
- Hospital charges and accommodation.
- Dental and optical benefits.
- Specialist fees.
- Exclusions, reimbursement limits and waiting periods.
If you will be employed in France, ask your employer about workplace complementary cover before buying a separate policy.
International Private Health Insurance
Private insurance may be appropriate where you do not yet have statutory entitlement or need additional international cover. Choose a policy based on your actual eligibility and anticipated care, including any ongoing treatment.
An EHIC covers necessary state-provided healthcare during eligible temporary stays. It should not be assumed to replace the arrangements required when establishing residence abroad. See the EU guidance on health cover for temporary stays.
‼️ – For emergencies in France: Call 112
Education in France
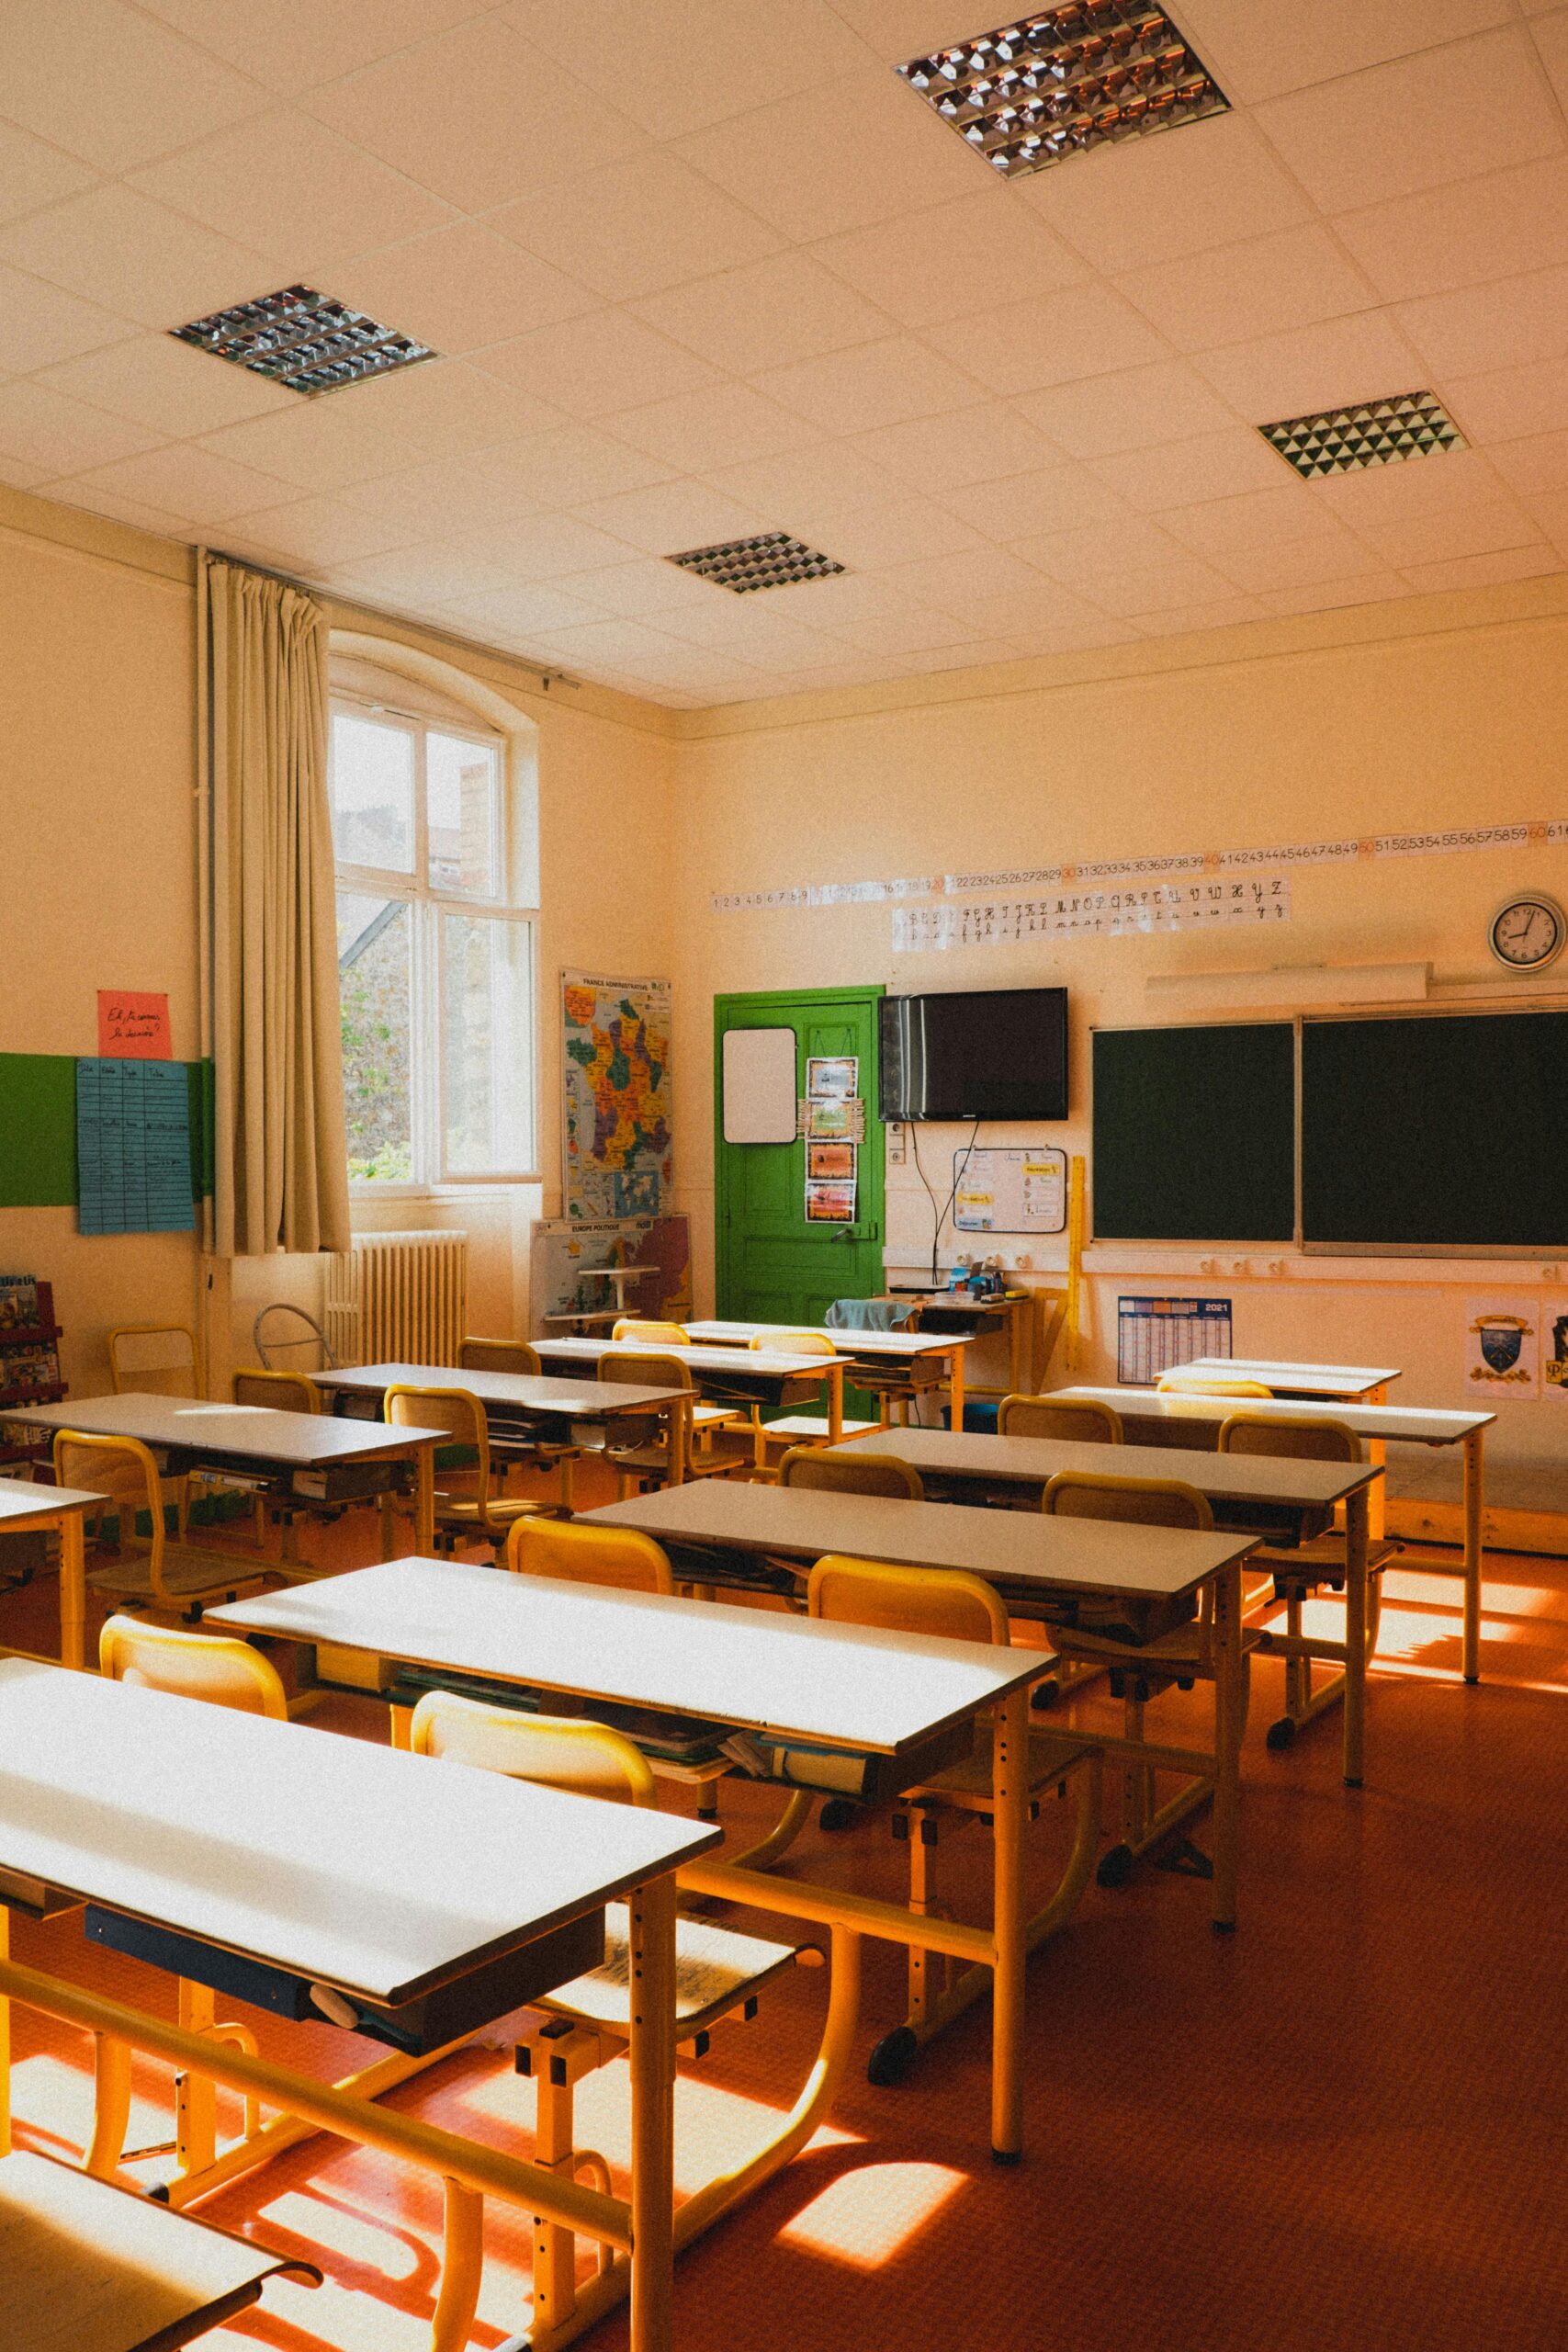
Moving to a new country can be an exciting but challenging experience, especially when it comes to finding the right education system for your children. Therefore, it’s important to know what your options are.
In France, education is mandatory between the ages 3-16.
France has a unique yet diverse educational system that caters to both French citizens and expats:
- École Maternelle (Preschool): Ages 3–6, focusing on early learning and socialization.
- École Élémentaire (Elementary School): Ages 6–11. covering fundamental skills.
- Collège (Middle School): Ages 11–15. Four years of “collège unique”, a unified program designed to offer the same curriculum to all students, regardless of ability
- Lycée (High School): Ages 15–18. Students choose between general, technological, or vocational streams, concluding with the baccalauréat (France’s national diploma of education).
Public schools
Public schools in France are free for French citizens and EU nationals. However, the curriculum is taught in French, and children may need additional language support.
International schools
France offers various international schools that offer an international curricula (e.g.: International Baccalaureate). Tuition fees can be quite high, ranging from €10,000 to €25,000 per child per year.
Higher Education
Dutch citizens generally qualify for the same national registration-fee rates as French students at relevant public institutions, rather than the differentiated rates that can apply to non-EU students.
Costs still depend on the institution and programme. Private institutions, business schools and certain specialist courses can charge considerably more. Check the academic year concerned, any student-life contribution and exemption rules through Campus France’s tuition-fee guidance.
Practical Tips for Settling In
Prioritise the language you will use immediately: arranging appointments, discussing a tenancy, speaking to teachers and explaining a household problem.
Useful phrases include:
- Bonjour: Hello.
- Merci: Thank you.
- S’il vous plaît: Please.
- Parlez-vous anglais ? Do you speak English?
- Pouvez-vous répéter, s’il vous plaît ? Could you repeat that, please?
- Je voudrais prendre rendez-vous: I would like to make an appointment.
Keep a short list of vocabulary relevant to your family, work and healthcare needs.
Give yourself time to learn how your new neighbourhood works. Check shop opening hours, transport services, market days and local activities.
Before choosing a home, try the journeys you expect to make regularly. If you are accustomed to cycling in the Netherlands, assess the actual routes between your prospective home, workplace and schools.
Include practical settling-in tasks in your plan: meter readings, insurance, internet installation, healthcare registration and delivery access.
Choose activities you can attend regularly, such as a sports club, language class, volunteering opportunity or parents’ group.
Dutch and international communities can provide useful support during the transition. Local associations also offer opportunities to practise French and meet people beyond your existing network.
Planning Your Move to France
A successful relocation starts with a clear picture of your residence rights, healthcare arrangements, budget and preferred location.
Give yourself time to organise the departure from your Dutch home as well as your arrival in France. If the dates do not align, discuss temporary accommodation and storage before finalising transport.
Speak to Crown Relocations about coordinating your packing, moving and storage requirements around your plans.
FAQs - Moving to France
No. Dutch citizens benefit from EU free-movement rights. Conditions apply to residence beyond three months, depending on whether you are working, studying or financially independent. Non-EU residents of the Netherlands must check their own requirements. French residence guidance.
There is no single figure that reliably represents the country. Compare current listings for your preferred neighbourhood, property size and tenancy type. Check whether charges are included and budget separately for utilities, insurance and upfront moving expenses.
Yes, where they meet the relevant conditions. Your route may be through French employment, qualifying residence or an S1 entitlement funded by another country. Confirm your arrangements before leaving. EU healthcare guidance.
Around three to six months is a useful starting point for a straightforward move. Allow longer where school admissions, a property purchase, specialist healthcare arrangements or immigration applications are involved. Work backwards from your fixed commitments and leave flexibility around delivery.
